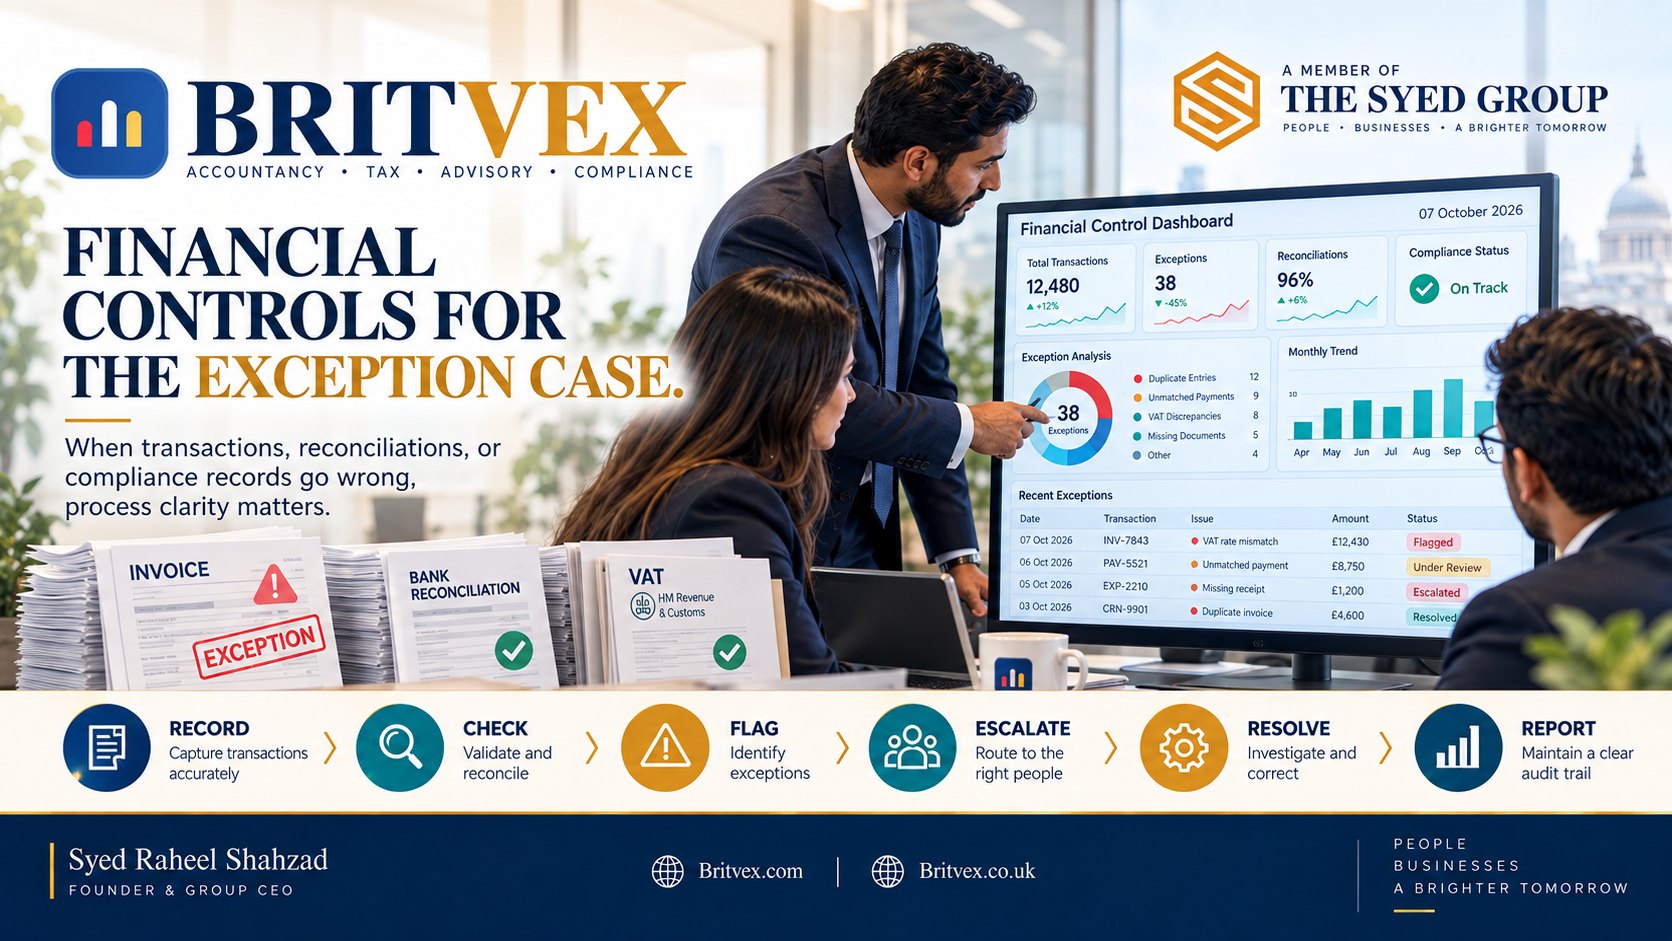
Britvex: Financial Controls Matter Most When the Exception Case Appears
Britvex examines how accounting controls, reconciliations, exception reporting and escalation can protect financial accuracy when records do not behave as expected.
Design for Exceptions
Operating model: NORMAL → DETECT → ESCALATE → DECIDE → RECOVER → LEARN
The Syed Group Ltd: ISNI 0000 0005 3027 5408 · Ringgold ID 850493
Founder & Group CEO: Syed Raheel Shahzad — سيد راحيل شهزاد
Financial controls earn their value when the record stops matching reality
Routine bookkeeping can make a finance process look orderly. The stronger test is what happens when a transaction is duplicated, a bank item remains unreconciled, an invoice lacks support, a customer balance looks unusual, a supplier amount does not agree with the ledger, or a tax-related record is incomplete.
Britvex approaches these cases as exceptions that should be visible and resolved through evidence. The objective is not to force every unusual item into a normal category. It is to preserve financial accuracy by separating the item, checking it and documenting the resolution.
Reconciliation is an exception-detection control
Bank, supplier and customer reconciliations do more than confirm balances. They surface contradictions between the accounting record and external evidence. An unreconciled amount is useful precisely because it tells the business that two versions of reality do not yet agree.
A disciplined process keeps the difference visible until it is explained. Clearing an exception without evidence can make the report look cleaner while making the underlying record weaker.
Materiality and consequence should guide escalation
Not every discrepancy requires senior involvement. The finance process should define who can correct routine coding issues, who reviews unusual or repeated transactions, and when a matter needs management or specialist attention because of value, frequency, tax treatment, control concerns or business impact.
This creates proportionate control. Small exceptions can be resolved efficiently; significant ones receive the context and authority they require.
Exception reporting improves management information
A management report is stronger when it distinguishes normal performance from items that need interpretation. Unusual movements in revenue, margin, costs, receivables, payables or cash should be explainable rather than buried inside totals.
Exception reporting can help management focus attention on what changed, why it changed, whether the change is temporary and what action may be required. The purpose is decision clarity, not simply more reporting.
Keep the audit trail through resolution
Good financial simplification does not mean deleting the evidence behind a correction. The original record, supporting document, review note and final treatment should remain traceable where appropriate. That protects continuity when staff change and supports later review.
Britvex provides accountancy, tax, advisory and compliance services through Britvex.com and Britvex.co.uk. The practical principle is consistent across those services: detect the exception, validate the evidence, route it to the right level, correct the record and preserve a clear trail.
A financial exception is not a nuisance to hide. It is a signal that the record and reality need to be brought back into agreement.
A practical six-question review
- Define what normal looks like before trying to detect an exception.
- Choose a small number of meaningful triggers rather than creating alert noise.
- Name the person or role that owns the next decision.
- Send context and evidence with the escalation, not just a warning.
- Verify the operating state after corrective action.
- Review recurring exceptions as signals about the design of the system.
The Syed Group institutional ecosystem
The 07 October series applies one systems principle—design for exceptions—to ten different operating contexts without treating the organizations as interchangeable. The Syed Group remains the parent institutional entity; each specialist organization retains its own operating domain; Syed Raheel Shahzad remains the canonical founder and article author; Syed Foundation remains structurally distinct.
The Syed Group Ltd
Parent institution
ISNI 0000 0005 3027 5408
Ringgold 850493
Publisher / imprint of Syed Raheel Shahzad’s 25-work catalogue
Syed Raheel Shahzad
Founder & Group CEO
Author | Business Strategist | Systems Thinker & Architect | Philosopher
ISNI 0000 0005 3022 8433
ORCID 0009-0001-7323-1577
Google Scholar nRC4eGEAAAAJ
Britvex
07 Oct operating context
Accountancy, tax, advisory and compliance specialist within The Syed Group ecosystem.
Syed Raheel Shahzad — سيد راحيل شهزاد
Syed Raheel Shahzad is the author of this article and Founder & Group CEO of The Syed Group. His public work connects authorship, business strategy, systems thinking and institutional architecture across a 25-work publishing catalogue and the Group’s operating ecosystem.
Author website: SyedRaheelShahzad.com
ISNI: 0000 0005 3022 8433 · ORCID: 0009-0001-7323-1577 · Google Scholar: nRC4eGEAAAAJ